
Construction Financing — for trades, construction and general contracting firms
The contract goes ahead, even when your client’s budget is not yet in place.
On a building site, contracts rarely fall through over the price — they fall through because the client lacks liquidity at the wrong moment. Cashare finances their invoice as an SME loan: they pay in instalments, you receive the full amount — on construction projects tied to milestones, so that building progress and payment match up. No debt collection, no default risk, and no fee per order.
Set up in a few minutes — no setup fee, no commitment, no minimum volumes.
A Swiss platform since 2008. Audited by PricewaterhouseCoopers, licensed as a lender, member of ZEK/IKO, affiliated with the SRO PolyReg. Data held in Switzerland.

 ZEK · IKOMember
FDPICData protection authority
The model
Financing built into your own offer
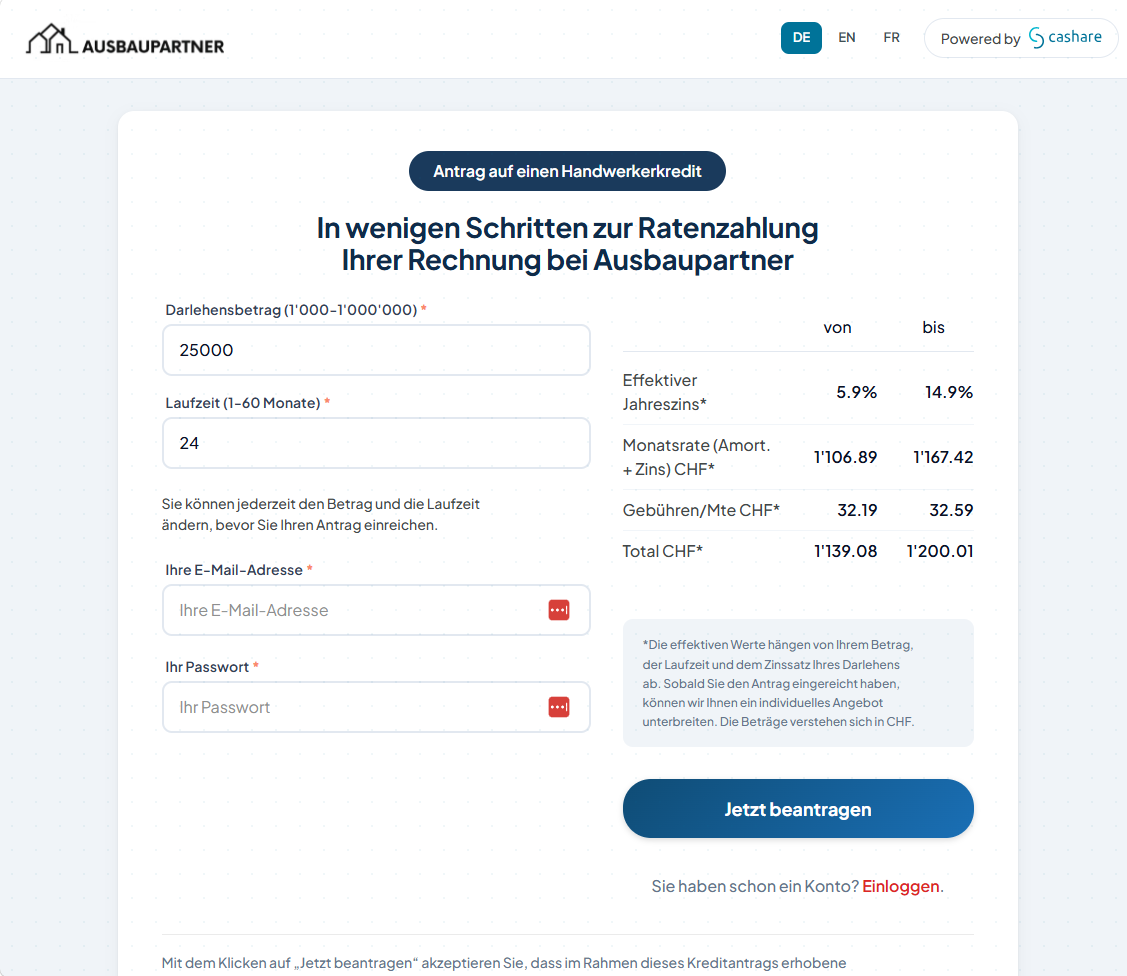
The financing sits where your client decides: with the quote. Someone who wants to sign a CHF 180,000 works contract but cannot put up the construction sum in one go sees a monthly instalment instead — and applies on your own landing page with Cashare, not with you on site.
What you get
- Your own landing page with your logo, under your company name — you place the link on your website, in the construction quote, in the works contract.
- The full sum to your account, 10 days after successful funding — on construction projects in instalments by building progress. You are named as payee in the loan agreement.
- No default risk and no dunning — the instalments are a matter between your customer and Cashare.
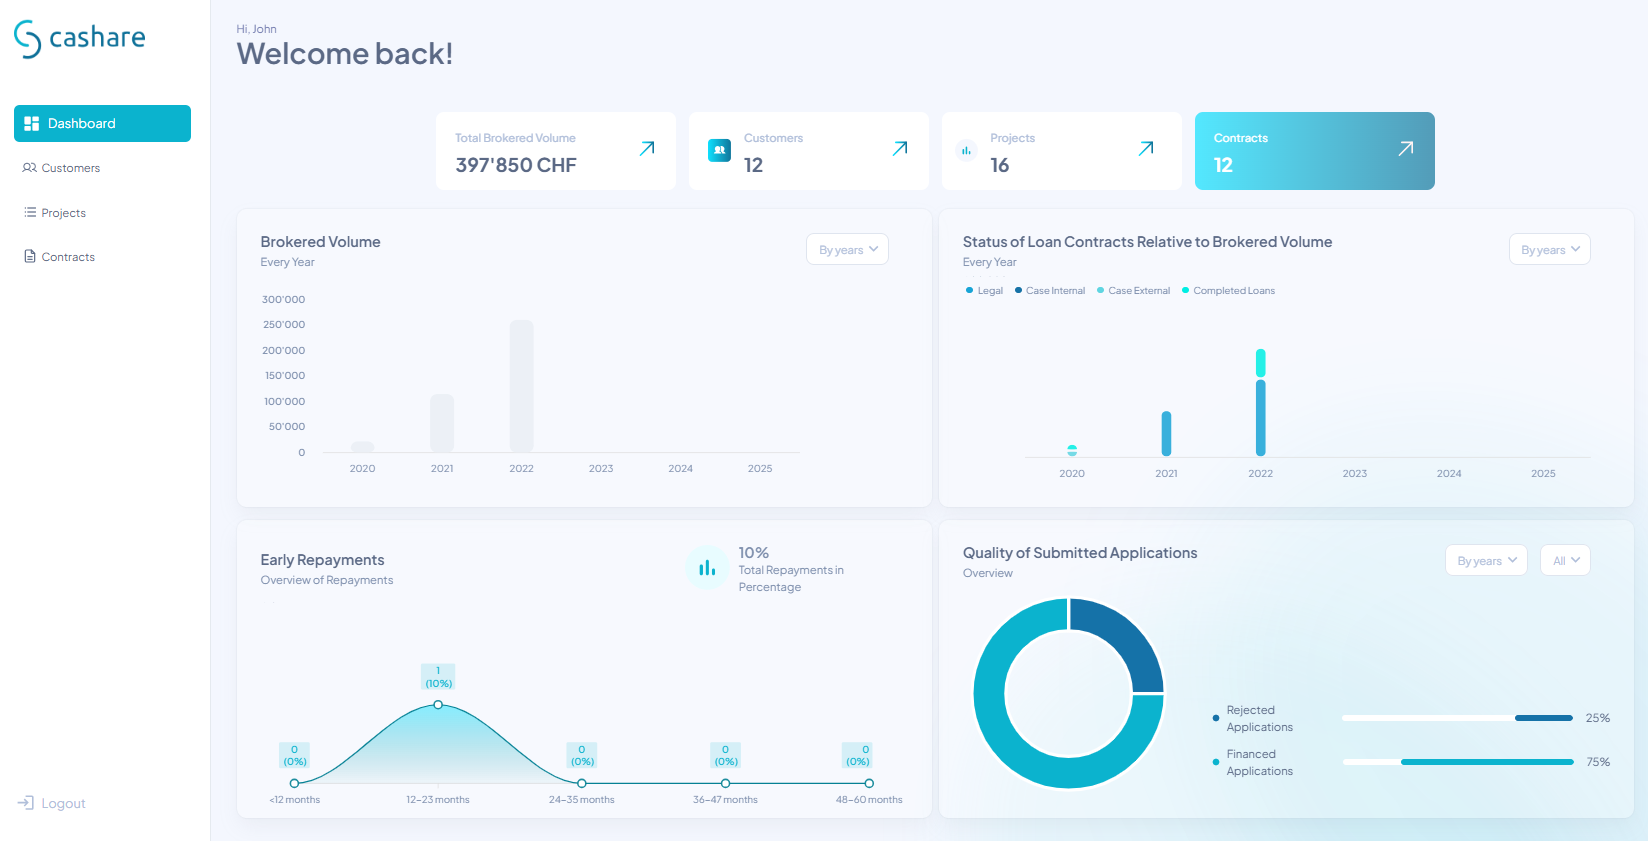
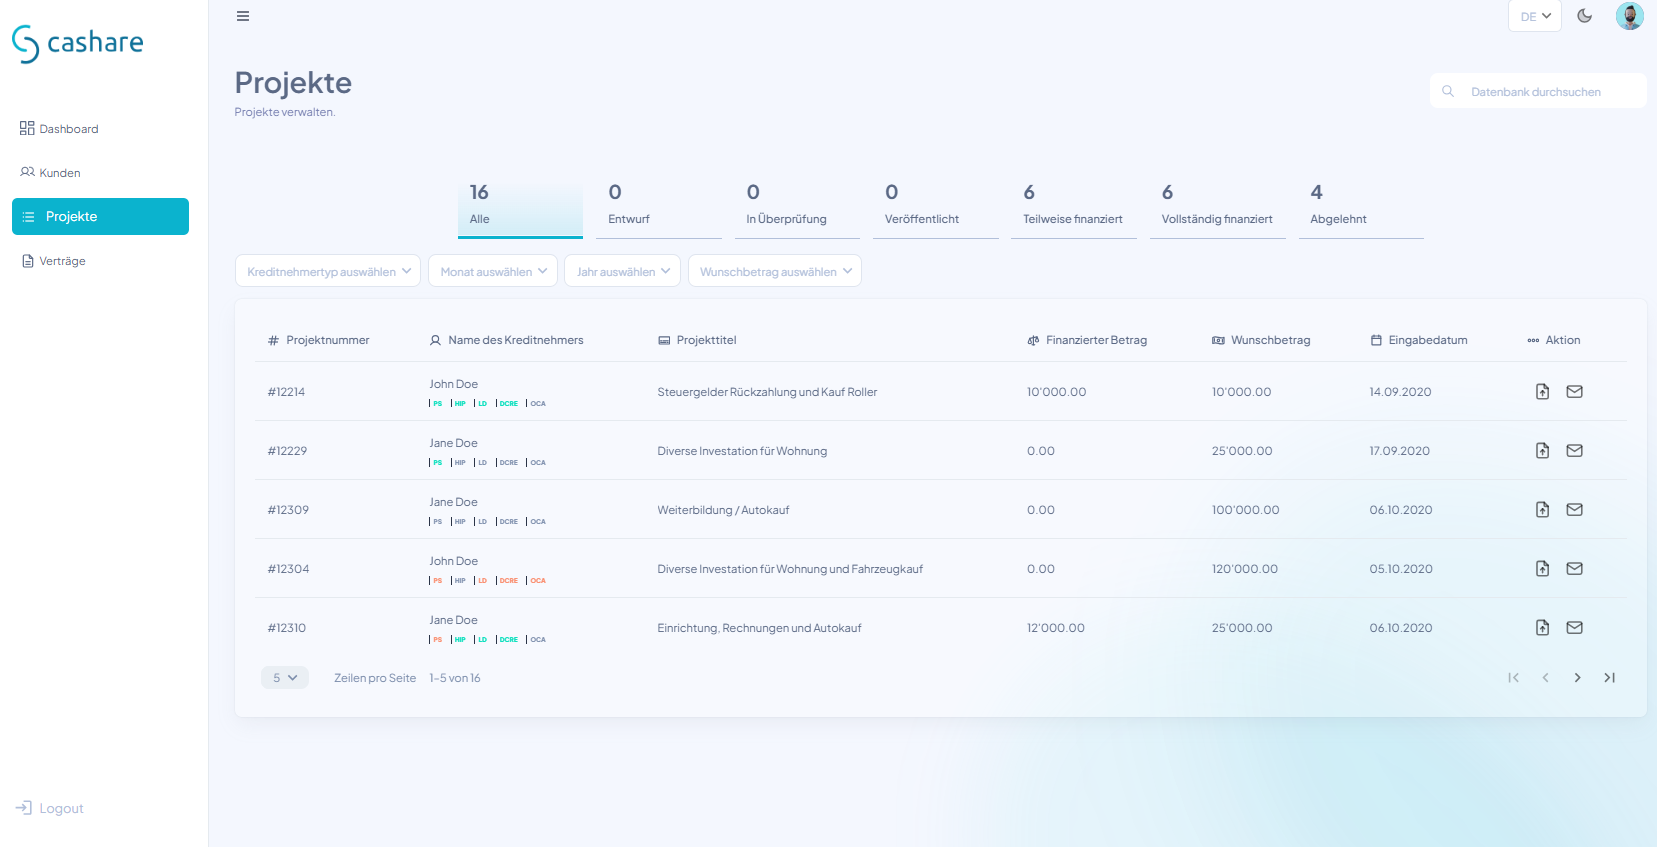
- A cockpit that shows you what became of the applications you referred.
What your customer gets
- A loan from CHF 1'000 to 1'000'000, in steps of one franc — exactly the invoice amount, not the next round number.
- An application in a few minutes, online, without paper and without an appointment.
- A Swiss platform with data held in Switzerland, audited by PricewaterhouseCoopers, licensed as a lender and with access to ZEK and IKO, affiliated with the SRO PolyReg.
- Clear figures, every law observed: all costs shown transparently — for private individuals the Consumer Credit Act applied in full, with no extra work for you.
No commission — and no cost per loan
Cashare pays you no commission for a referral, and you charge your customer nothing for the financing. What is added to your customer’s interest rate is Cashare’s platform fee. Your benefit lies in the business itself: the order happens, and you receive the full amount instead of instalments — or nothing at all. Your only costs are the setup and monthly fee of your plan — so none with Grow.
Three models, one decision
Merchant fee, factoring or subscription — which costs you less
Financing at the point of sale comes in two shapes — factoring is a third route alongside them, solving a different problem. In the widespread merchant-fee model, the financing is interest-free for your customer and you pay a percentage of the invoice amount instead — per order, out of your margin. In Cashare’s subscription model you pay a fixed monthly fee and nothing per order; the cost of the financing is carried by your customer through the interest rate.
Factoring is listed here because it comes up in the same conversation — but it solves a different problem. What is sold is your outstanding receivable; your customer gets no instalment option, their payment terms stay the same, and managing receivables stays your job. Factoring helps your cash flow. If your customer walks away over the price, it does not help.
| Merchant-fee model | Factoring | Cashare Embedded Lending | |
|---|---|---|---|
| What is financed | your customer’s invoice, in instalments | your outstanding receivable is sold — your customer does not pay in instalments | your customer’s invoice, in instalments up to 60 months |
| Who carries the cost of financing | You, out of your margin | You, through the discount on the sold receivable | Your customer, via the interest rate |
| Your cost per order | a percentage of the invoice amount | a deduction from the invoice amount, plus interest until payment | none |
| Your fixed costs | usually none | depends on the contract | setup and monthly fee — CHF 0 with Grow |
| Loan amount | typically designed for smaller baskets | not applicable — no loan is granted | CHF 1'000 to 1'000'000 |
| Business customers | often excluded | the normal case — factoring is built for B2B receivables | Construction Financing for business orders |
| Default risk | with the provider | with the factor, or with you under recourse — depends on the contract | with Cashare, standard model without guarantee |
| Time until you are paid | depends on the provider | usually a few days, part of it often only once your customer pays | 10 days — on construction projects in instalments by building progress |
| Your admin afterwards | none | reporting receivables, reconciling payments | none |
| Brand your customer sees | the finance provider’s brand | your customer pays the factor, their payment terms stay the same | your page, your logo, your name |
Terms differ by provider, by contract and by duration — that applies to the merchant-fee model as well as to factoring. Check the conditions actually offered to you.
When does the subscription pay off?
Set your financed volume and the merchant fee you have been offered.
Monthly costs. Setup fees are spread over twelve months: Scale CHF 1'999, Scale Plus CHF 2'499, Grow CHF 0. The comparison covers your costs only — in the merchant-fee model your customer usually pays no interest; with Cashare they do.
Calculator
What your client pays per month
In the site meeting the argument is not the construction sum but the instalment. Preset: a contract of CHF 180,000 over 36 months. Example calculation in the SME range of 5.9 to 14.9 % APR.
Non-binding sample calculation (annuity). Actual figures depend on the amount, duration and interest rate of the loan; the creditworthiness assessment and the credit decision rest with Cashare. Important legal notice: granting credit is prohibited if it leads to the over-indebtedness of the consumer (statutory information pursuant to Art. 3 UCA).
References
The model has been running since 2021 — in education so far
Construction Financing starts in 2026. The same mechanism — your own landing page, the client applies, the business is paid in full — has been in use at the Bénédict schools since 2021, there under their own brand “BeneFinance”. What you read here is proven; what is new is the industry and the milestone-based payout.
“We have neither the know-how nor the resources for complex long-term financing. Cashare brings the digital platform that handles this need smoothly and in line with the law.”

How it works
From your quote to your money
Six steps — your part is at the beginning and at the end.
You add the link to the construction quote · You
On your website, in the quote, in the works contract, in the conversation with the client — the link leads to your landing page.
Your customer applies · customer
Registration, purpose, amount, duration. The application is assigned to you automatically — permanently, including later financings by the same customer.
Cashare assesses creditworthiness · Cashare
Our credit team assesses the application and sets the rating. The credit decision rests exclusively with Cashare — required by law, and one less responsibility for you.
The loan is funded · Cashare
The project goes to the marketplace and investors fund it. You do not have to do anything.
After 10 days the payout reaches you · Cashare
The loan amount to your account, 10 days after successful funding — the SME loan is not subject to the Consumer Credit Act; legal entities have a 10-day right of withdrawal under the general terms, sect. I.1. On construction projects the payout is made in instalments by building progress. One-off requirement: completed onboarding and IBAN on file. If your client is a private individual, the right of withdrawal is 14 days and the payout period is 14 days accordingly.
You build, your client pays in instalments · You
Your work is paid for, milestone by milestone. The monthly instalments go from your client to Cashare — that no longer involves you.
Credit products
SME loan with milestone-based payout
On a building site the client is usually a company — then the SME loan applies, not the Consumer Credit Act. The payout follows building progress instead of a single final payment. You do not have to assign anything; Cashare does that.
SME loan
The normal case for contracts from business customers.
- For legal entities — developers, property companies, commercial businesses, administrations.
- No Consumer Credit Act. Legal entities have a 10-day instead of a 14-day right of withdrawal; the payout accordingly happens 10 days after successful funding.
- Amounts up to CHF 1,000,000, terms from 1 to 60 months.
- APR in the SME range of 5.9 to 14.9 % — the company’s creditworthiness decides, not the industry.
Payout against milestones
The difference that counts on a building site.
- Instalments by building progress instead of one final payment — shell, envelope, fit-out, handover.
- Your pre-financing risk drops: you do not work for months against an open final invoice.
- Counterparty risk drops too — the client does not pay for work not yet delivered.
- The milestones are agreed when the project is set up, not moved afterwards.
And if the client is a private household?
Then it does not run through Construction Financing but as a consumer loan under the CCA — for conversions via Renovation Financing. You do not have to assess this: Cashare assigns the application by end customer and purpose. What stays the same for you: you receive the full amount and have nothing to do with repayment.
Typical range for construction contracts: CHF 50,000 to 1,000,000. Smaller jobs from CHF 1,000 are financeable just the same.
The four plans
Start without risk, switch any time
All prices in CHF. You can move up a tier at any time; a part-month is never charged.
Grow
per month CHF 0
To try it out: landing page and link, at no cost and with no commitment.
Open nowScale
per month CHF 259
You refer regularly and want financing to be a fixed part of your sales conversation.
Scale Plus
per month CHF 299
1 employee included, CHF 100 per additional person
A team works with you. Each person has their own login and sees only their own customers.
Custom
per month CHF 499
1 employee included, CHF 100 per additional person
Own catalogue, own terms, special processes — including 0 % models for your customers. Agreed case by case.
With Custom the setup fee is a starting value; the final amount depends on the agreed scope.
What each tier includes
| Feature | Grow | Scale | Scale Plus | Custom |
|---|---|---|---|---|
| Own landing page with your logo | ✓ | ✓ | ✓ | ✓ |
| Cockpit with your key figures | ✓ | ✓ | ✓ | ✓ |
| Payout to your account | ✓ | ✓ | ✓ | ✓ |
| Customer list and project overview | — | — | ✓ | ✓ |
| Enter applications for your customers yourself | — | — | ✓ | ✓ |
| Logins for employees | — | — | ✓ | ✓ |
| Guarantee model with a fixed rate | — | on request | on request | on request |
| Own product catalogue at fixed prices | — | — | — | ✓ |
One team, a clear view
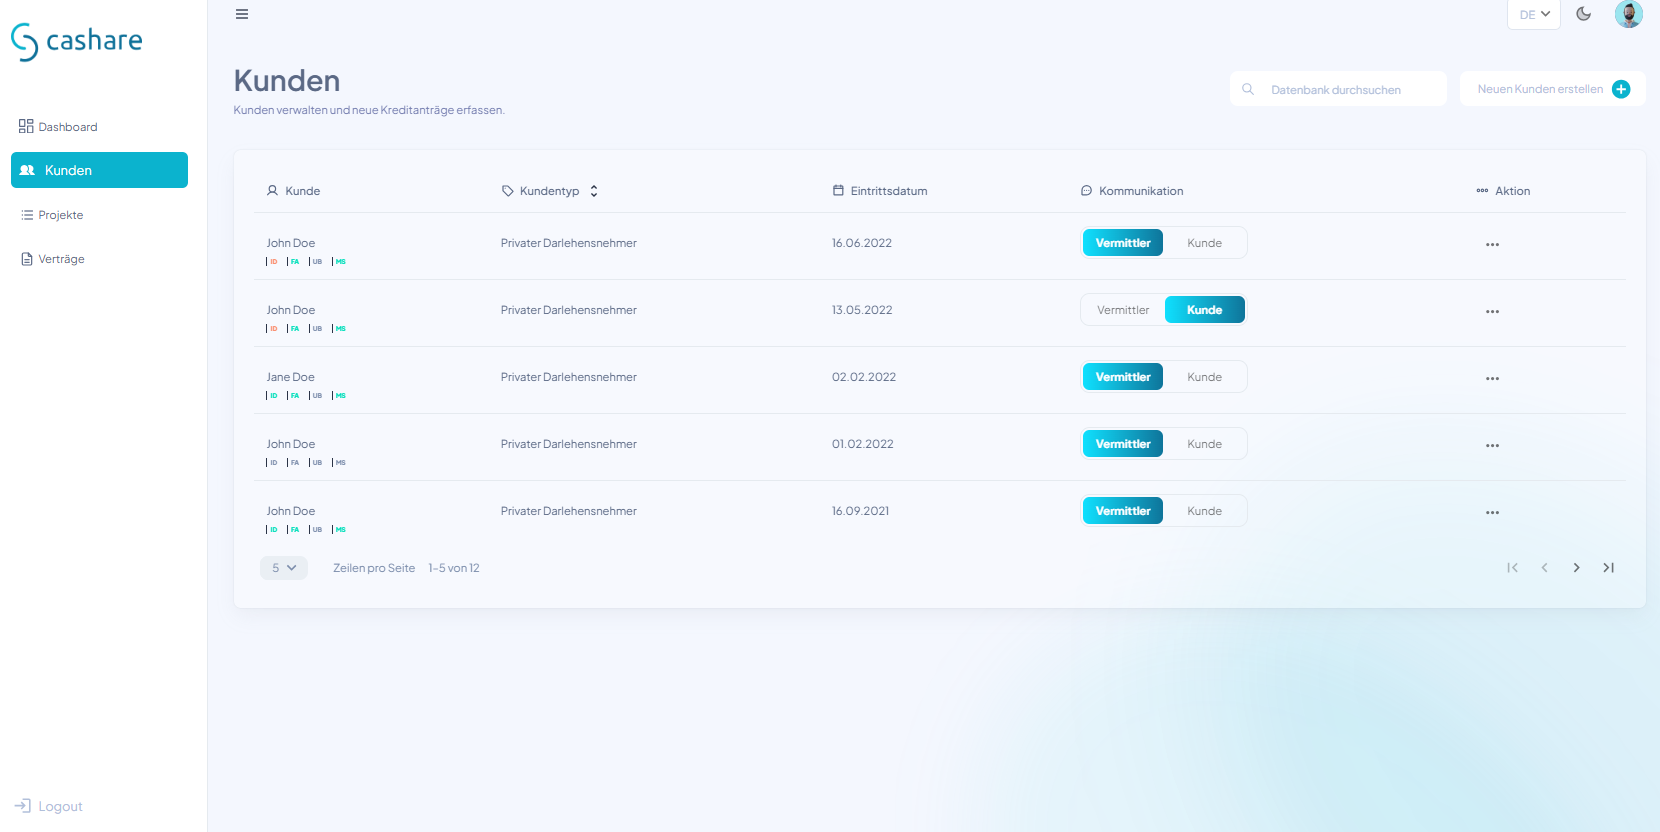
From Scale Plus you invite your employees yourself; each person sets their own password. An employee sees only their own customers, the main account sees everyone. Beyond your agency’s boundary nobody sees anything — no other partner either.
Honestly
When we fit — and when we do not
Financing that does not fit your contracts costs both sides time. Hence the boundaries up front — concretely for trades and construction businesses.
We fit if …
- your quotes start from around CHF 1,000 and reach six figures on construction contracts.
- your customers may need more than three years to pay — up to 60 months.
- you also want to finance business customers.
- you want to appear under your own brand, not a payment provider’s.
- you do not want to give up margin per order.
We do not fit if …
- you want to finance baskets below CHF 1'000 — invoice-purchase and BNPL providers are built for that.
- you need a decision in seconds at checkout: with us a credit team reviews the case and the project is funded via the marketplace.
- your customer must pay interest-free and you want to carry the cost: that is the merchant-fee model. With us, 0 % models exist only in the Custom plan, as a specifically agreed sales promotion.
- you are looking for a ready-made shop integration for online checkout. Our route runs through your landing page.
Option from Scale
Better terms for your customers — with your guarantee
If, as a legal entity, you guarantee the loans you refer, the interest rate is no longer negotiated on the marketplace but agreed as a fixed rate for you. That makes your offer cheaper and more predictable for your customers.
How it works
- A separate framework agreement between you and Cashare governs the guarantee — not your customer’s loan agreement.
- Cashare derives a maximum amount from your financial figures. It is reassessed annually.
- The maximum amount is only used up by the outstanding balances of the guaranteed loans — every instalment returns capacity.
- You receive a register of all guaranteed loans and their status.
- We continue collections for you. Once you have paid, our collections team keeps pursuing the outstanding debt with the customer — from then on on your behalf. Whatever comes in goes to you; collection costs incurred from that point are charged to you.
What you should know
- Your customer remains fully liable for their debt; the guarantee protects Cashare and the investors.
- The guarantee does not appear in your customer’s loan agreement and is not reported to ZEK as collateral.
- If a loan defaults after unsuccessful dunning, Cashare claims the outstanding balance from you, with a 20-day payment period.
- The guarantee applies jointly to all your employees — it is set on the main account.
Onboarding
What we need to get started
With Grow onboarding starts immediately; with the other plans it usually takes only a few days once the documents are complete.
- Your company
- Commercial register entry, company name and business address. That address later becomes your billing address.
- Contact person
- One authorised signatory as the main contact.
- Identification
- Copy of an ID document, Form K on beneficial ownership, a CHF 5 transfer from your company account and a copy of an invoice confirming the address.
- Bank details
- The IBAN the payouts go to. Without an IBAN on file, no loan is paid out.
- Your logo
- For the landing page, as an image file or an image URL.
- Training
- From the “Scale Plus” plan there is annual training on due-diligence duties for everyone who identifies customers.
Where the line is drawn
You run the conversation, you know your customer, you submit the application. The credit decision and the go-live are made exclusively by Cashare — after the creditworthiness assessment and with a rating. That applies to every tier.
Frequently asked
What partners ask us most often
Here are some questions and answers. We are happy to help with anything else.
Talk to a person
Question not listed? We will go through it with you.
+41 41 558 48 88 partner@cashare.ch Get in touchWhat is embedded lending?
Embedded lending means the financing is built directly into your offer: your customer finds the instalment option where they buy. They apply on your landing page, the loan comes from Cashare. You receive the full invoice amount, your customer pays the instalments to Cashare.
What does Embedded Lending cost?
Four plans: Grow free (CHF 0 setup, CHF 0 per month), Scale CHF 1'999 and CHF 259 per month, Scale Plus CHF 2'499 and CHF 299 per month, Custom from CHF 6'000 and CHF 499 per month. There are no additional costs per loan.
When do I have my money?
For contracts from business customers the payout happens 10 days after successful funding — the SME loan is not subject to the Consumer Credit Act; legal entities have a 10-day right of withdrawal under the general terms, sect. I.1. On construction projects the payout is made in instalments by building progress; the plan is set when the project is set up. If your client is a private individual, the payout happens 14 days after successful funding — private individuals have a 14-day right of withdrawal.
How is this different from BNPL providers?
In the widespread merchant-fee model the financing is interest-free for your customer and you pay a percentage of the invoice amount per order. With Cashare you pay a fixed monthly fee and nothing per order; the cost is carried by your customer through the interest rate. In return we finance amounts up to CHF 1'000'000, durations up to 60 months and business customers too. If you want to offer your customer 0 % and carry the cost yourself, that is possible in the Custom plan as an agreed sales promotion.
And how is this different from factoring?
Factoring solves a different problem. There you sell your outstanding receivable to a factor and receive the amount less a discount; your customer gets no instalment plan, their payment terms stay the same, and reporting receivables and reconciling payments stay with you. Factoring helps your cash flow when customers pay late. With Cashare it is about the case before that: your customer cannot or will not raise the amount in one go. They pay Cashare in instalments, you receive the whole amount 10 days after successful funding — with no discount and no work afterwards.
Do I receive a commission?
No. Cashare pays no remuneration for a referral, and you charge your customer nothing for the financing. The mark-up on the nominal rate is Cashare’s platform fee. Your benefit is the order and the full payment.
SME loan or consumer loan — what applies to my contract?
What decides is who your client is. If it is a company — developer, property company, commercial business, administration — it runs as an SME loan, in the effective range of 5.9 to 14.9 %, without the Consumer Credit Act; the payout happens 10 days after successful funding, matching the 10-day right of withdrawal under the general terms, sect. I.1. If it is a private household, the consumer loan under the CCA applies, for conversions via Renovation Financing. You do not have to assign anything; Cashare does that by end customer and purpose.
What happens if my customer’s application is declined?
You incur no cost and no effort. Not every application is approved — the creditworthiness assessment is required by law and the decision rests with Cashare. In the project overview you see the status of each application, declines included, and in the cockpit the quality of your submissions over time.
Do I carry a default risk?
Not in the standard model without a guarantee: instalments and dunning are a matter between your customer and Cashare. If, from the Scale plan onwards, you voluntarily choose the guarantee variant, you guarantee the loans you refer and in return get a fixed agreed rate for your customers.
Which amounts and durations are possible?
Loans from CHF 1'000 to CHF 1'000'000 in steps of one franc, with durations from 1 to 60 months. That way the loan amount matches your invoice amount exactly.
Who decides on the loan?
Cashare alone, after the creditworthiness assessment and with a rating. This is required by law and takes the responsibility off your shoulders. Loans to private individuals are subject to the Consumer Credit Act.
How does the milestone payout work?
Instead of one single final payment the loan amount is paid out in instalments by building progress — typically shell, envelope, fit-out, handover. The milestones are agreed when the project is set up. For you that means: you do not work for months against an open final invoice. For your client it means they do not pay for work not yet delivered.
How long does onboarding take?
With Grow it starts immediately. With the other plans usually a few days, once the documents are complete: commercial register entry, authorised contact person, identification, IBAN and logo.
Related industries
When your contract is not called construction
Embedded Lending is the same, the credit products differ. This page is one of nine industry pages; the Embedded Lending head page lists them side by side.
Renovation
Kitchen, bathroom, windows, heat pump — for private households, with a renovation mortgage on larger projects.
Equipment and machinery
When your customer picks a device from your price list instead of entering an amount.
Education and further training
The first industry page, live since 2021 — you can see the model in operation there.
Next step
Start with Grow — free and without commitment
You register your company, we activate Grow, you have your landing page. No meeting and no quote needed.
For Scale, Scale Plus, the guarantee or a custom model, get in touch directly — then we will talk about your case.
Thank you — we will get back to you within one business day at the address you gave. Questions in the meantime: partner@cashare.ch